Military & VA Home Buying
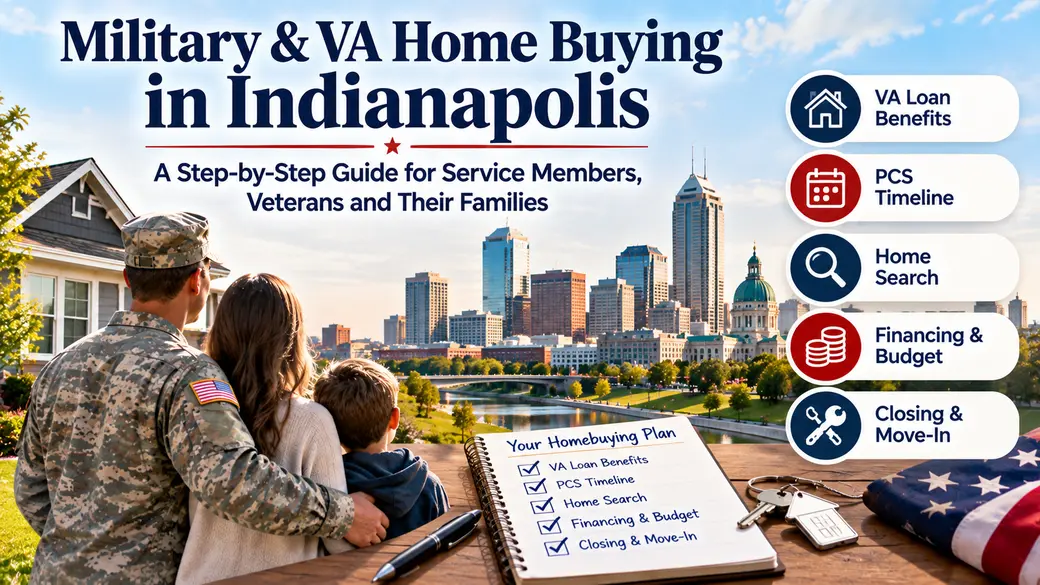
Military & VA home buying in Indianapolis requires a plan that can move with PCS orders, deployments, and changing tour lengths. Military families and Veterans can reduce pressure by confirming loan eligibility early, setting a realistic timeline, and choosing a home location that supports the daily routine after arrival.
Military & VA Home Buying - How VA Financing Works
A VA-backed home loan can allow eligible borrowers with full entitlement to buy a primary residence with no down payment and no private mortgage insurance. Begin by obtaining a Certificate of Eligibility, commonly called a COE, which helps a lender confirm your available VA home loan benefit. Eligibility, income, credit, and occupancy requirements still apply, so the COE is an important first step rather than a final approval.
VA loans are made by private lenders and guaranteed in part by the Department of Veterans Affairs. That structure can make homeownership more accessible for qualified service members, Veterans, and eligible surviving spouses, while lenders still evaluate the household's complete financial picture.
The VA funding fee is another cost to discuss with a lender before making an offer. Some borrowers, including many Veterans receiving service-connected disability compensation, may be exempt. Funding-fee rules can change, so review current guidance through the VA home loan eligibility information before finalizing your financing plan.
VA financing is designed for a home you intend to occupy as your primary residence. Orders, deployments, and other military circumstances can affect occupancy timing, so raise those details with your lender as early as possible.
Planning a Purchase Around PCS Orders
The strongest PCS purchase plan starts before the reporting deadline becomes urgent. Once an assignment is likely, gather income documents, request your COE, compare lenders, and establish a monthly payment range that leaves room for moving costs, savings, and everyday expenses.
Buying before arrival can work well when your household has clear priorities and a reliable local process. Remote video tours, detailed property disclosures, neighborhood conversations, and electronic document delivery can help you narrow choices from another duty station. Decide in advance which features are nonnegotiable, such as bedroom count, parking, yard space, commute tolerance, or proximity to regular errands.
Waiting until after arrival provides a different advantage: you can drive likely routes, experience traffic at the times you would actually travel, and get a better feel for the areas that fit your routine. This can be especially useful when your work location, reporting schedule, or family logistics are still being finalized.
For Indianapolis buyers, start by confirming the location you will visit most often, then compare homes using real travel routes rather than a simple map radius. Check morning and evening drive times, road construction notices, access points, and the locations of schools, childcare, groceries, medical care, and recreation. A home search for Indianapolis-area listings can help organize options once your location and budget priorities are clear.
Choosing a Home Near Your Duty Station
The right Indianapolis location is one that supports your daily schedule, not merely one that looks close to your destination on a map. Compare likely commute times, major road access, traffic patterns, parking needs, and the practical stops your household will make throughout the week.
A shorter drive may create more time at home, but it is only one part of the decision. Some military households prioritize a larger yard, flexible work-from-home space, room for visiting family, storage for equipment, or a layout that can adapt if the assignment changes. Others may prefer a lower-maintenance property that makes a future move easier.
Neighborhood fit should also include the routines that matter after the first week in the home. Visit at different times when possible, note street activity and lighting, and consider how the home's location affects errands, school transportation, recreation, and support networks. Individual school options should be researched based on the needs of each household, rather than relying on broad assumptions about an entire area.
Indianapolis offers a mix of established homes and newer construction, so buyers should compare condition, maintenance expectations, lot size, and travel patterns alongside price. A home that fits a shorter assignment may look different from one you may keep for several years. Match the purchase to the expected length of stay while preserving flexibility for changing orders.
First-Time Buyer Essentials for Military Households
A first-time military buyer should budget for the full cost of ownership, not only the principal and interest payment. Include property taxes, homeowners insurance, utilities, routine maintenance, moving expenses, and an emergency reserve when comparing homes in Indianapolis.
Basic Allowance for Housing can be an important part of monthly cash flow, but it should not be the only factor behind a purchase decision. A sustainable payment leaves room for savings, travel, vehicle costs, family needs, and the unexpected expenses that can accompany a move. Use a home affordability calculator to test different purchase prices and payment assumptions before beginning serious home tours.
Preapproval should come before writing offers because it clarifies the financing range a lender is prepared to consider. It also gives buyers time to ask questions about VA loan terms, funding fees, closing costs, and documentation requirements without a contract deadline creating extra pressure.
Earnest money is typically submitted after an offer is accepted and becomes part of the transaction process. Closing costs can include lender charges, title services, prepaid insurance or taxes, and other settlement expenses. VA rules limit certain charges that may be paid by the buyer, while seller contributions may be possible within applicable guidelines.
The goal is not to borrow the maximum amount available. It is to choose a home that supports the household through a PCS, deployment, career change, or future relocation.
Whether you're using VA financing or exploring other mortgage options, understanding the full homebuying process can help you prepare for a smoother transition. From choosing the right neighborhood to budgeting for inspections and closing costs, our guide to navigating the homebuying process in Indianapolis offers additional insights to help you make informed decisions before purchasing your next home.
Buying on a Short Timeline
A compressed PCS timeline can still support an organized home purchase when responsibilities and deadlines are clear from the start.
- Schedule remote tours around lender milestones and your reporting date.
- Ask for live video that shows exterior areas, storage, room flow, and features that may not appear in listing photos.
- Keep key financial and military documents accessible for secure electronic delivery.
- Identify who can review documents or make decisions if travel or deployment interrupts the process.
- Confirm remote-closing requirements with the lender, title professionals, and all required signers early.
- Maintain a backup housing plan in case the purchase timeline changes.
Buy or Rent After a PCS?
Buying after a PCS can make sense when the expected stay, household budget, and home choice align. A longer assignment may give owners more time to settle in and absorb the costs associated with purchasing and later selling a home.
Renting may offer more flexibility when the tour is short, orders are uncertain, or the household needs time to learn the area. Future rental potential can be part of the analysis, but it should not be the sole reason to buy. Consider whether you would be comfortable owning from another duty station, whether property management would be needed, and how a future mortgage payment would fit your finances.
The VA Appraisal and Home Inspection Serve Different Purposes
A VA appraisal is not a home inspection because it focuses on value and VA property requirements rather than providing a detailed assessment of visible condition. The appraisal helps the lender determine whether the home's value supports the loan and whether it appears to meet applicable VA minimum property requirements.
A home inspection is a separate buyer choice and is strongly recommended for most purchases. An inspector reviews accessible, visible components of the property and can help buyers understand maintenance needs, safety concerns, and possible repair costs before they commit to ownership.
Military buyers on tight timelines should schedule both processes promptly after an accepted offer, allowing time to review findings and discuss next steps with the appropriate professionals. The two services answer different questions: the appraisal supports the financing decision, while the inspection helps the buyer make an informed property decision.
Remote buyers should ask for clear documentation, detailed photos, and direct explanations of material findings. If travel prevents an in-person visit, arrange a live video conversation about the property so that the buyer can ask questions in real time.
Planning for Your Next Military Move
Buying a home during a PCS move involves more than finding the right property. From VA financing and remote tours to closing timelines and future relocation plans, every detail matters. AMR Real Estate helps military families and veterans explore Indianapolis homes with guidance tailored to their schedules, budgets, and long-term goals. Whether you're purchasing before arrival or preparing for your next assignment, connect with AMR Real Estate for a friendly, no-pressure conversation about your homebuying options.
FAQ
Is Indianapolis a good place to live?
Indianapolis can be a practical choice for military and VA buyers who want varied home styles, established neighborhoods, and access to a large metro area's services and employment base. The best fit depends on your confirmed work location, commute preferences, housing budget, and the routines that matter most to your household.
Is Indianapolis expensive?
Indianapolis costs vary significantly by neighborhood, property type, age of the home, taxes, insurance, and commute needs. Rather than relying on a broad affordability label, compare full monthly payment estimates for homes in the specific areas you are considering.
What salary do you need in Indianapolis?
There is no single salary requirement for buying a home in Indianapolis because qualification depends on income, recurring debts, loan terms, available entitlement, and the home's full monthly cost. A lender evaluates your individual financial profile, while your personal budget should also account for savings and moving expenses.
Can I use my VA loan more than once?
Yes, eligible borrowers may use VA home loan benefits more than once when entitlement is available. Full entitlement is commonly restored after the prior VA-financed home is sold and the loan is paid off, although your lender can explain how your individual circumstances apply.
Do I need a down payment with a VA loan?
Eligible borrowers with full entitlement may be able to purchase with no down payment. The final loan structure can depend on available entitlement, lender requirements, and the purchase details, so confirm those terms before making an offer.
Can I buy a home before I arrive at my new duty station?
Yes, you can buy before arriving by using live virtual tours, electronic documentation, and a well-organized local process. Confirm occupancy timing, financing documents, and closing logistics early so the transaction aligns with your PCS schedule.
Does a VA loan require a home inspection?
No, VA financing requires an appraisal, not a home inspection. An inspection is still strongly recommended because it gives buyers a more detailed review of visible property condition and maintenance needs.
Categories
Recent Posts