Indianapolis Home Buyer's Guide: A to Z
Buying a home in Indianapolis is one of the biggest financial decisions you will make, and every part of the process is local. Reported sales across the Indianapolis postal-city area had an aggregate median sale price of $247,000, while the June 2026 median reached $276,593.50 (Indianapolis, IN). This Indianapolis Home Buyer's Guide explains how to build a workable budget, prepare financing, compare areas, evaluate properties, make an informed offer, and move toward closing with confidence.
Indianapolis Real Estate at a Glance
Reported sales activity shows that Indianapolis pricing and transaction volume can shift by month, neighborhood, and property condition (Attom Data, as of 2026-07).
| Metric | Current reading |
|---|---|
| Aggregate reported median sale price | $247,000 |
| Aggregate reported homes sold | 23,297 |
| June 2026 homes sold | 1,960 |
| June 2026 median sale price | $276,593.50 |
What the Indianapolis Housing Market Looks Like Right Now
Indianapolis is a mixed market, meaning buyers may find negotiating room on some homes while well-priced, move-in-ready properties can still draw prompt interest. The strongest competition tends to center on homes with current finishes, functional layouts, reliable maintenance records, and prices that align with recent nearby sales.
The reported median sale price moved from $225,000 in January 2026 to $276,593.50 in June 2026, a pattern that reflects both seasonal activity and the wide range of homes sold across the postal-city area. A citywide median is useful for context, but it is not a price target for every buyer. A renovated bungalow, a newer subdivision home, and a downtown condominium can each follow different supply and demand patterns.
For first-time buyers, the practical question is not whether every listing will be competitive. It is whether the homes that fit your payment range are receiving attention quickly. Buyers who know their maximum payment, have current loan documentation, and understand their preferred locations can respond more confidently when the right home appears.
Move-up buyers should also weigh the cost of added space against long-term upkeep. Larger homes, custom features, pools, and specialty lots can bring higher insurance, maintenance, and utility obligations. The local market snapshot may help frame a conversation about current pricing and timing.
Is Indianapolis a Buyer's or Seller's Market Right Now?
Indianapolis offers a property-by-property balance rather than one answer for every buyer.
- Reported June 2026 activity included 1,960 home sales across the Indianapolis postal-city area.
- The June 2026 median sale price was $276,593.50, compared with $225,000 in January 2026.
- Competition is often strongest for homes that are updated, realistically priced, and ready for occupancy.
- Buyers entering today benefit from a verified budget, a current pre-approval, and a firm maximum offer before they begin touring.
Step 1: Set a Realistic Budget Before You Search
A realistic Indianapolis purchase budget starts with the monthly payment you can sustain comfortably, not simply the maximum amount a lender may approve. Begin with gross household income, recurring debt, savings goals, transportation, childcare, utilities, maintenance, and the cash you want to retain after closing.
Your estimate should include principal and interest, property taxes, homeowners insurance, possible mortgage insurance, and any homeowners association dues. Indiana owner-occupied homesteads generally fall under a property-tax cap of 1% of gross assessed value, although deductions, assessed value, and eligibility can affect the final bill. The Indiana Department of Local Government Finance explains the state’s property-tax cap rules.
HOA expenses deserve separate attention. A condominium, townhome, or planned community may charge monthly dues for shared services, amenities, or exterior maintenance. A detached home may have no HOA at all. Before relying on a payment estimate, review what the fee covers, whether reserves appear adequate, and whether special assessments are possible.
Pre-qualification is an early estimate based largely on information you provide to a lender. Genuine affordability is more personal. It means the payment still leaves room for savings, repairs, emergencies, travel, and ordinary household expenses. Comparing several payment scenarios with a mortgage calculator can help clarify a comfortable range before you tour homes.
Monthly Cost Breakdown by Price Point in Indianapolis
The examples below assume 20% down, a 30-year fixed mortgage rate of 7.32%, and a 1% owner-occupied property-tax illustration. The rate is from Freddie Mac’s Primary Mortgage Market Survey dated October 22, 2026. Insurance, mortgage insurance, HOA dues, lender fees, and property-specific expenses can change the final payment.
| Purchase price | Estimated mortgage payment (30-yr fixed at current rate) | Property tax | Insurance | Total estimated monthly cost |
|---|---|---|---|---|
| Entry-level: $250,000 | About $1,369 | About $208 | Property-specific quote | About $1,577 plus insurance |
| Median reported price: $247,000 | About $1,353 | About $206 | Property-specific quote | About $1,559 plus insurance |
| Move-up: $400,000 | About $2,190 | About $333 | Property-specific quote | About $2,523 plus insurance |
Step 2: Get Pre-Approved Before You Search in Indianapolis
Pre-approval helps Indianapolis buyers demonstrate that a lender has reviewed key financial documents, not merely discussed a possible borrowing range. It also keeps your search focused on homes that fit verified income, assets, credit, and debt obligations.
Gather recent pay stubs, W-2 forms or tax returns, bank statements, identification, proof of down-payment funds, and details about recurring debt. Self-employed buyers may need business returns or additional documentation. Avoid taking on new debt, changing jobs, or moving large sums of money without discussing the change with your lender first.
A pre-qualification generally relies on information supplied by the buyer. A pre-approval usually involves a deeper review of documentation. Neither is a final loan commitment, but a pre-approval can make an offer easier for a seller to evaluate when a desirable listing receives quick attention.
Military and VA-eligible buyers should confirm eligibility, occupancy rules, lender requirements, and documentation early. The Consumer Financial Protection Bureau’s preapproval guidance explains what a pre-approval letter represents and why comparing loan options matters.
Step 3: Choose the Right Area of Indianapolis for Your Lifestyle and Budget
The right Indianapolis area is the one that supports your daily routine, preferred home style, and sustainable payment. Neighborhood-level conditions can differ substantially by property type, updates, lot size, commute patterns, and access to amenities.
Downtown and near-downtown neighborhoods can suit buyers who value restaurants, cultural venues, sporting events, and access to central employment areas. Housing may include condos, townhomes, renovated historic homes, and smaller-lot properties. Walkability and proximity to activity are key differentiators, while parking availability, HOA costs, and building maintenance require close review.
Irvington and established east-side neighborhoods may appeal to buyers who want mature trees, architectural character, and an established residential setting. Homes can vary widely in condition from one block to the next. First-time buyers may find opportunities here, but they should look carefully at renovation quality, drainage, mechanical systems, and likely future updates.
Broad Ripple and nearby north-side areas can work well for buyers who prioritize trails, neighborhood activity, dining, and access to major corridors. The housing stock ranges from older bungalows to renovated properties and newer infill. Walkability is a meaningful draw, while lot size, parking, and street activity can vary sharply.
Outer Indianapolis neighborhoods and newer subdivisions may fit move-up buyers seeking larger garages, more square footage, contemporary layouts, or dedicated home-office space. The tradeoff can be longer drives for work and errands. Review HOA rules, development plans, and builder documents before making assumptions about future nearby construction.
Step 4: Search Strategically and Evaluate Properties
An effective Indianapolis home search begins with priorities that cannot change: your maximum monthly payment, preferred areas, minimum bedroom count, commute limits, and acceptable condition level. Keep a separate list for flexible preferences such as paint colors, fixtures, or landscaping.
Use current local listing information and saved search criteria to watch for homes that match your budget and goals. Set alerts for new listings, price reductions, and homes that return to the market. The Indianapolis home search can help buyers organize listings by property type, price range, and basic features.
At each showing, look beyond staging and consider how the home will function in everyday life.
- Compare room sizes, storage, parking, and outdoor space with your actual routines.
- Look for visible moisture, uneven floors, drainage concerns, aging systems, and deferred maintenance.
- Ask about the roof, heating, cooling, windows, plumbing, and electrical components.
- Visit the street at different times when possible to notice traffic, noise, lighting, and nearby activity.
- Review seller disclosures and nearby comparable sales before deciding what the home is worth to you.
Indianapolis includes homes from many construction eras. Older properties can offer established locations and character, while newer homes may provide contemporary layouts and fewer immediate updates. Both require attention to property-specific maintenance, community rules, and future costs.
Step 5: Make a Competitive Offer in Indianapolis
A competitive Indianapolis offer is one that fits the home, the seller’s priorities, and your financial limits. Price matters, but a clear financing plan, realistic timing, and carefully selected terms can also influence how an offer is received.
Start with recent comparable sales, the home’s condition, days on market, and any price changes. A newly listed, move-in-ready home may call for a direct offer with limited unnecessary requests. A property that has been available longer may create room to discuss price, seller concessions, possession timing, or targeted repairs.
Earnest money is negotiated in the purchase agreement, so there is no single required amount for every Indianapolis transaction. Understand the deposit terms, deadlines, and circumstances affecting those funds before you sign. An escalation clause can be useful in a documented multiple-offer situation, but it should always include a firm maximum that fits your budget.
Other negotiating levers include flexible possession, a complete financing package, and requests focused on substantial property concerns rather than a long list of minor items. Buyers should also consider how quickly they can respond to lender and title requests. The strongest offer is not automatically the highest one. It is a well-supported offer that you can comfortably honor.
Pro-Tip: The most common offer mistake is raising the price before reviewing comparable sales and the full monthly payment. Set a firm maximum first, then let the property evidence guide your negotiation.
Step 6: Inspections, Due Diligence, and Closing in Indianapolis
The period after an accepted offer is when buyers confirm the property, financing, title details, and final cash needed for closing. Your purchase agreement controls the deadlines, so keep a written calendar of each required date and decision.
Buyers commonly review seller disclosures, arrange a general home inspection, confirm lending details, and order specialized evaluations when the home’s age, location, or visible condition warrants them. Depending on the property, that may include roof, sewer-line, wood-destroying-organism, radon, or system-specific evaluations. If material concerns arise, the parties may negotiate a resolution permitted by the contract.
A title company typically coordinates title work, settlement paperwork, and the transfer process. Your lender provides a Loan Estimate and later a Closing Disclosure, allowing you to compare loan terms and expected cash to close. Keep these documents available and ask questions whenever the figures or terms change.
Buyer closing costs can include lender charges, title services, prepaid insurance, property-tax items, and escrow funding. Costs vary based on the loan, contract terms, closing date, and property. Eligible buyers may explore programs through the Indiana Housing and Community Development Authority, subject to program requirements and participating-lender guidelines.
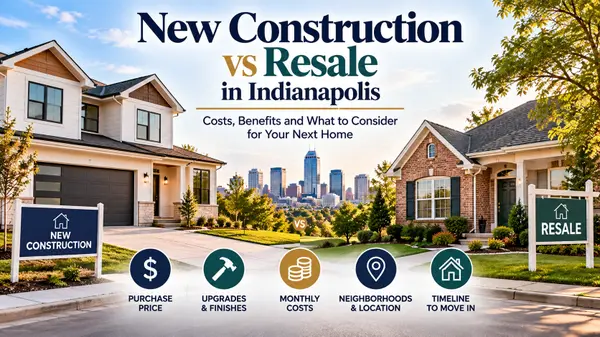
New Construction vs. Resale Homes in Indianapolis
| Consideration | New construction | Resale home |
|---|---|---|
| Typical price premium | May reflect newer materials, current designs, and selected upgrades | Varies by location, condition, and renovation level |
| Negotiability | May focus on upgrades, financing support, or completion timing | May focus on price, condition, possession, or seller priorities |
| Inspection considerations | A professional inspection can identify incomplete or defective work | Findings often relate to age, maintenance history, and deferred repairs |
| Customization options | May allow finish or layout selections before completion | Changes are generally made after closing |
| Move-in timeline | Depends on construction stage and builder schedule | Depends on seller possession and contract timing |
| Warranty coverage | Builder warranty terms should be reviewed in writing | Coverage depends on remaining warranties or optional plans |
| Financing differences | Rate-lock timing may need to fit the construction schedule | Financing generally follows the contract-to-closing timeline |
Ready to Buy in Indianapolis?
AMR Real Estate works with buyers across Indianapolis at a range of price points, from first-time buyers building a budget to move-up buyers preparing competitive offers. Call or text (317) 506-6925 for a no-pressure conversation about your timeline, preferred home features, and next steps.
Frequently Asked Questions: Buying a Home in Indianapolis
How much do I need for a down payment to buy in Indianapolis?
The amount depends on your loan program, credit profile, purchase price, and savings. A 20% down payment is one common benchmark for conventional financing, but eligible buyers may qualify with a smaller down payment. The Consumer Financial Protection Bureau recommends comparing loan options, monthly payments, and total borrowing costs before selecting a program.
How long does it take to buy a home in Indianapolis from search to close?
The home search can take weeks or months, depending on your budget, location preferences, and the homes available when you begin. Once you have an accepted offer, many financed purchases close in roughly 30 to 45 days, although lender, title, and contract requirements can affect the schedule. Build enough time into your plan to respond promptly to documentation requests.
Is Indianapolis a good place to buy a home right now?
Indianapolis can be a sensible place to buy when the home, payment, and expected ownership period fit your goals. The June 2026 reported median sale price was $276,593.50, but conditions can differ significantly by neighborhood, property condition, and price point. A property-level comparison is more useful than relying only on a citywide market figure.
What are closing costs for buyers in Indianapolis?
Buyer closing costs can include lender charges, title services, prepaid insurance, property-tax items, and initial escrow funding. The final amount depends on the loan type, contract terms, property, and closing date. Indiana’s owner-occupied property-tax cap may help with monthly planning, but deductions and assessed value affect the actual tax bill.
Do I need a buyer's agent in Indianapolis, and what does it cost?
A buyer’s agent can help you compare homes, coordinate showings, prepare offers, negotiate terms, and manage transaction deadlines. Representation terms, services, and compensation should be discussed in writing before you begin touring homes. Clear expectations allow you to decide what level of support fits your purchase.
Categories
Recent Posts