First-Time Home Buying Tips for Military Families
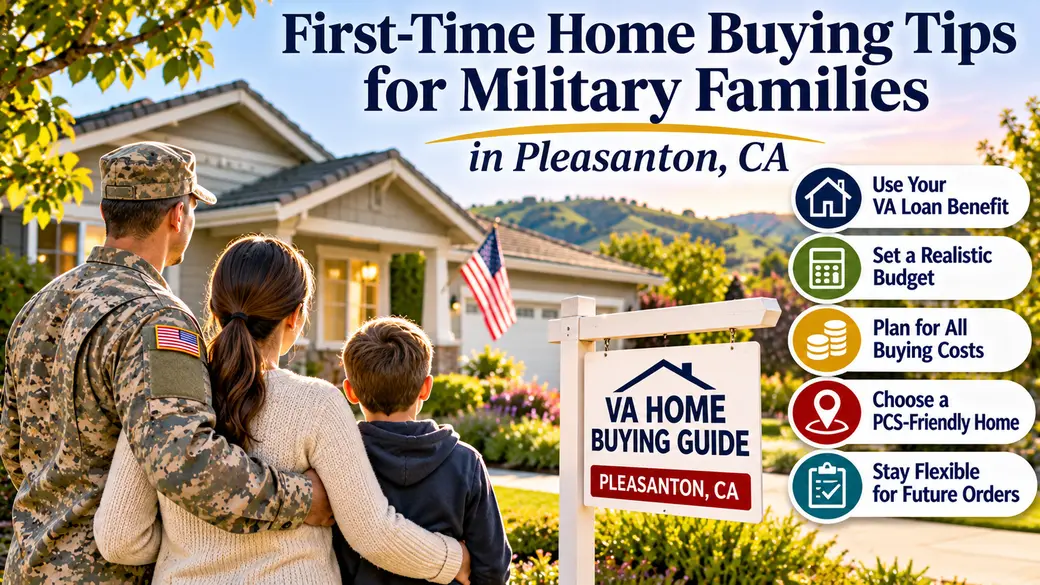
Buying a first home while serving is exciting, but it comes with choices civilian buyers may not face. The best first-time home buying tips for military families are to understand VA financing, choose a payment that protects flexibility, and select a home that can still work if PCS orders change your plans.
Understand Your VA Loan Benefit
Eligible service members, veterans, and qualifying surviving spouses may be able to use a VA-backed loan with no down payment and no monthly mortgage insurance. Start by requesting a Certificate of Eligibility, or COE, because it confirms the VA entitlement available for your loan application.
A VA loan is not automatic approval. Your lender will still evaluate income, credit, occupancy plans, debts, and the property itself. The benefit can reduce an important upfront barrier, but a realistic budget and complete documentation still matter.
The VA funding fee is a one-time program cost that may be paid at closing or financed into the loan balance. Some eligible borrowers, including certain veterans receiving service-connected disability compensation, may qualify for an exemption. Review the VA funding fee and closing-cost rules before comparing offers so you understand the total cost of each loan option.
For military families planning to purchase a home in Indianapolis, understanding how VA financing works alongside PCS timelines and local housing considerations can make the process easier to navigate. From preparing loan documents to evaluating properties and coordinating a move, each decision benefits from a clear plan. Explore our guide to using VA benefits when buying a home in Indianapolis for additional insights into financing, relocation preparation, and homebuying considerations.
Set a Budget That Fits Military Life
A military-friendly home budget uses BAH as a guide, not the highest payment your household can take on. A lender's approval amount reflects lending standards, while your budget should leave room for savings goals, household routines, travel, and the possibility that one income or assignment could change.
Begin with the costs included in a typical monthly payment. These may include principal and interest, property taxes, homeowners insurance, association dues, and required loan-related charges. Then add the expenses that may not appear in that payment estimate, such as electricity, water, internet, furnishings, lawn care, commuting, and routine maintenance.
A separate reserve for repairs can make ownership less stressful. Older systems, larger yards, multiple stories, and specialized features may suit your family, but they can also require more time and money. Consider who could respond if an urgent repair happens while you are away for training, temporary duty, or deployment.
Test several price points with a payment calculator and compare the results with your everyday spending. Look at what remains after housing, food, transportation, savings, childcare, and travel costs. A payment that feels manageable on paper can become restrictive when insurance changes, a vehicle needs work, or a move creates overlapping expenses.
Think about the full rhythm of military life before choosing a price range. Could your household keep saving each month? Could you handle a repair without relying on new debt? Could a spouse's employment transition change the plan? A lower monthly obligation may not buy the largest home today, but it can preserve useful flexibility for the next set of orders.
Know the Real Costs of Buying
Buying a home requires cash planning beyond the down payment, including funds for earnest money, closing costs, prepaid items, moving, and a reserve after closing. VA financing can reduce the down-payment hurdle for eligible buyers, but it does not remove every expense connected to a purchase.
Earnest money is a good-faith deposit submitted after an accepted contract. Its amount, timing, and handling depend on the agreement. When a transaction closes, it is commonly applied toward eligible costs or funds due at closing, subject to the contract terms.
Closing costs may include lender charges, title services, recording charges, insurance-related expenses, and local transaction requirements. Ask for a detailed Loan Estimate early in the process, then compare the same categories across loan offers. A lower rate does not always mean a lower overall cash requirement.
Prepaid items are different from transaction fees. They can include advance homeowners insurance and initial deposits for future tax or insurance payments. Because those recurring costs may change, leave some breathing room in the household budget after closing.
Seller concessions can help with allowable closing expenses when they are negotiated into the contract and permitted by the loan program. They are not guaranteed, and they should be considered alongside the offer price, property condition, and local competition. A concession can reduce cash needed at closing, but it should still fit the full terms of the offer.
Keep moving costs and emergency savings separate from closing funds whenever possible. Military families may have travel, storage, vehicle, or temporary-housing expenses that arise around a move. Protecting a post-closing reserve gives your household more options when an unexpected cost appears shortly after receiving the keys.
Think About Your Next PCS Now
A PCS-friendly home is one that can remain manageable to own, rent, or sell if your next assignment changes the plan. The goal is not to predict the market or your orders perfectly. It is to choose a property with practical options if your household needs to move sooner than expected.
Start with payment resilience. Ask whether the monthly cost would remain workable during a job transition, a period of overlapping housing expenses, or an unexpected repair. A home that stretches the budget in a stable year may become difficult to carry during a relocation.
Next, consider rental practicality. Layout, condition, parking, storage, and access to everyday services can affect how broadly a property appeals to future renters. Think about whether you could cover maintenance, leasing costs, and a possible vacancy if you decide to keep the home after a PCS.
Remote ownership also deserves a plan. Decide who would coordinate repairs, tenant communication, routine upkeep, and local decisions if you move away. A manageable property with dependable systems and clear maintenance needs may be easier to oversee from another duty station.
For resale flexibility, look for features that serve many households rather than only your current preferences. A functional floor plan, usable storage, sensible outdoor space, and everyday convenience can have broader appeal than highly customized features. Condition matters, too, because deferred maintenance can narrow your options when a move becomes urgent.
Compare homes by property type, condition, location, and recurring costs across Indianapolis rather than limiting the search to one style. Before making an offer, picture three possible outcomes: staying longer than expected, selling after a few years, or renting from a distance. A thoughtful choice today can give your family more workable paths later.
Build the Right Team
The right team makes a military purchase more organized, especially when timing, travel, or remote communication adds complexity. Choose an agent who understands PCS timelines and can help you compare homes through the lens of budget, condition, and future flexibility.
Work with a lender experienced in VA-backed financing. Compare loan terms, document requests, funding-fee treatment, and closing timelines before selecting a lender. The VA explains how to request a Certificate of Eligibility, while a lender can explain how the benefit applies to your individual financial picture.
Finally, hire a qualified home inspector to evaluate the property's condition and explain findings clearly. That information can help you plan for repairs and maintenance before committing to ownership.
Common First-Time Mistakes to Avoid
First-time military buyers can avoid costly pressure by keeping the purchase focused on long-term affordability, property condition, and PCS flexibility.
-
Skipping the inspection: A home can appear move-in ready while still having maintenance needs that are difficult to spot during a showing. An inspection gives you a clearer view of the property's condition, likely repairs, and maintenance priorities. Read the report carefully and ask questions about items that could affect your budget, timeline, or ability to manage the home from a distance.
-
Maxing out the budget: The highest approval amount is not automatically a comfortable payment. Leave room for utilities, insurance changes, repairs, savings, travel, and normal family expenses. A lower monthly obligation can be especially valuable when military schedules change, a spouse changes jobs, or an unexpected trip affects the household budget.
-
Opening new credit before closing: New credit cards, vehicle loans, financed furniture, large purchases, or missed payments can change your debt profile while the lender completes its final review. Keep financial activity steady, pay bills on time, and ask your lender before making a significant purchase or moving money between accounts.
-
Ignoring the PCS question: Do not assume a home will be easy to sell or rent simply because it is in a desirable area. Consider maintenance demands, property condition, local demand, likely carrying costs, and whether your household could handle a vacancy or sale delay.
-
Focusing only on the house: Daily routines matter, too. Test the commute, visit at different times of day, and think through parking, storage, nearby services, and how the property supports your household during demanding military seasons.
Buying Your First Home in Indianapolis
Buying your first home becomes more manageable when you understand financing, protect your budget, and plan for a future move. For military families, the strongest decisions connect VA loan preparation, closing-cost planning, and a home choice that can remain practical through a possible PCS.
AMR Real Estate helps first-time military buyers in Indianapolis compare VA loan offers, closing costs, and PCS-friendly home choices with a plan built around their household timeline and priorities.
FAQ
Is Indianapolis a good place to live?
Indianapolis can be a practical place to live for first-time buyers who want a large metro area with varied housing and employment settings. The Indianapolis postal-city area has a population of 990,537, and its median home value is $277,129, which provides useful context for buyers comparing neighborhoods and property types (Indianapolis, IN). Visit prospective areas at different times, test the commute, and compare a home's condition and upkeep demands with your household routine.
Is Indianapolis expensive?
Indianapolis is generally less expensive than many large U.S. metros, but affordability depends on the neighborhood, home condition, taxes, insurance, and association dues. The local cost-of-living index is 95, with housing at 97, where 100 represents the national average, so costs are somewhat below the national benchmark overall (Indianapolis, IN). Compare the complete monthly payment and expected maintenance needs rather than judging affordability by list price alone.
What salary do you need in Indianapolis?
There is no single salary required to buy a home in Indianapolis because affordability depends on the purchase price, loan terms, household debts, savings, and recurring expenses. The area's median household income is $69,169, but your workable price range should be based on your own income, BAH, debts, emergency savings, and expected payment. Review a complete payment estimate with a lender before deciding on a target home price.
Is a VA loan good for first-time buyers?
A VA loan can be a strong option for eligible first-time buyers because it may allow no down payment and does not require monthly mortgage insurance. Other loan types may still make sense depending on your credit profile, purchase plans, available funds, and the terms offered by each lender. Compare the full monthly payment and total cash required, not just the down payment.
How much should I save before buying?
Save for closing costs, prepaid items, moving expenses, and an emergency fund, even if you expect to use a VA loan with no down payment. The right amount depends on your contract, loan terms, household needs, and how much flexibility you want after closing. Keeping a reserve separate from transaction funds can help you handle repairs or relocation-related costs.
Can a military spouse buy a home alone?
A military spouse may be able to buy a home alone, but eligibility and loan options depend on the loan type, income, credit, and VA entitlement rules. A spouse may apply independently, apply jointly, or use another financing option based on the household's circumstances. A lender can explain which documentation and qualification path fits the purchase.
Should I buy if I might PCS in two years?
Buying before a possible PCS can work when the payment is manageable and the home has realistic resale or rental potential. Consider property condition, likely maintenance, carrying costs, local demand, and whether you could manage the home from another location. Avoid relying on a guaranteed future sale price or rent amount when making the decision.
Categories
Recent Posts